
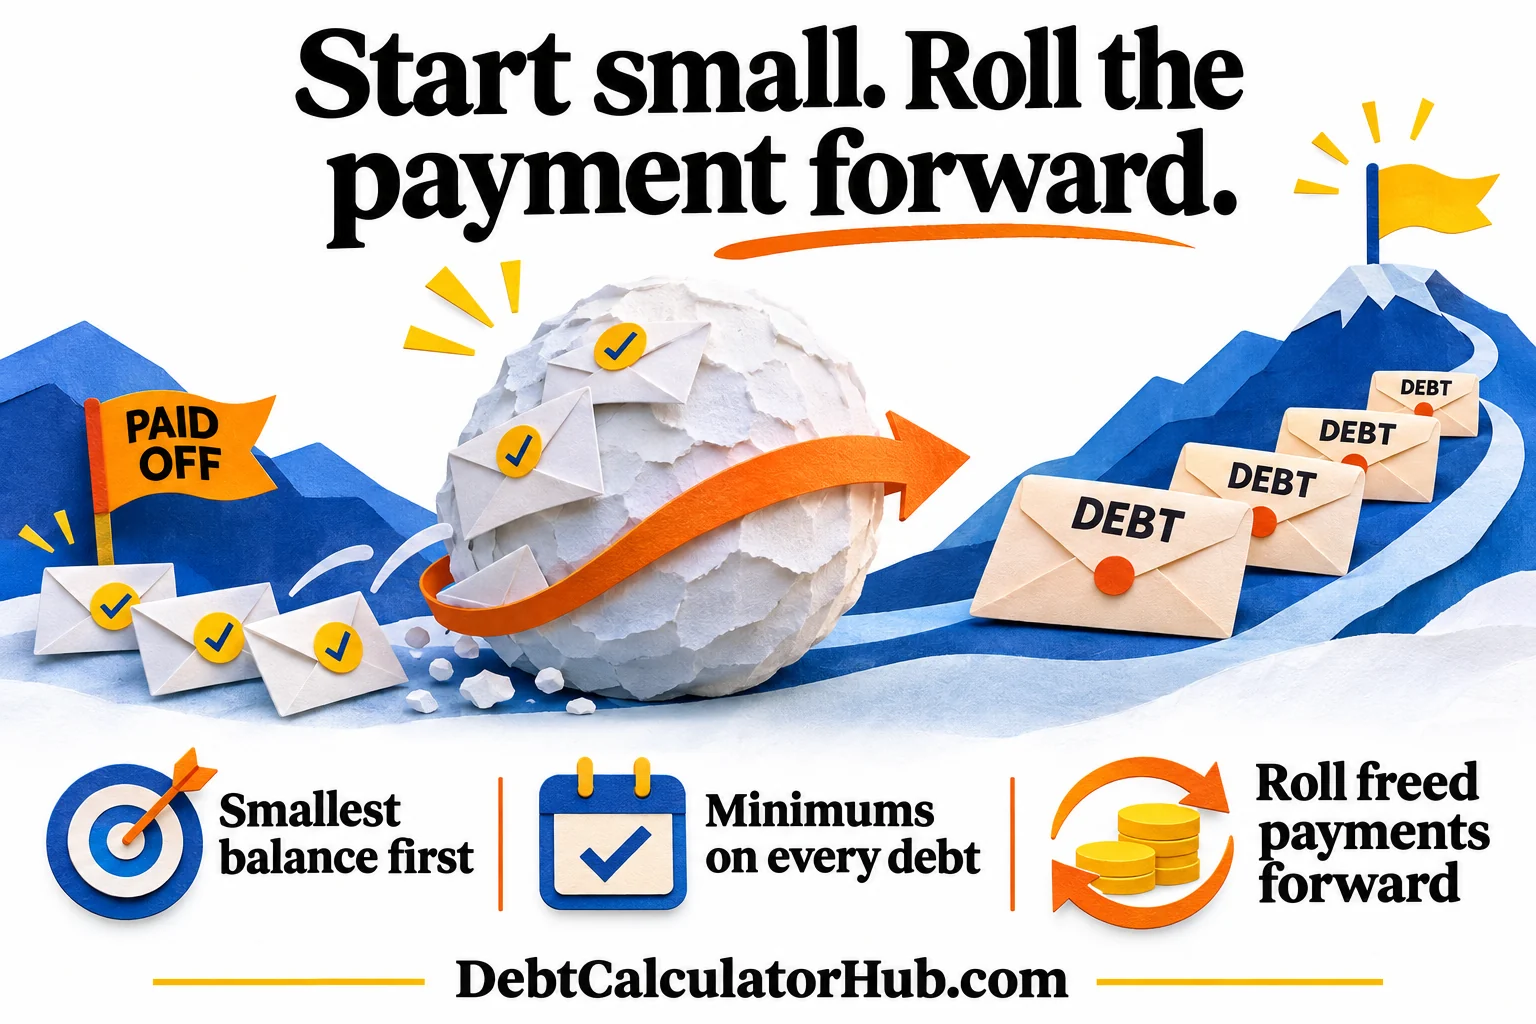
How the snowball method works
What is the debt snowball method?
The debt snowball method is a payoff strategy that focuses on behavior first. Instead of starting with the highest interest rate, you list your debts from the smallest balance to the largest balance. You keep making minimum payments on every debt, then send any extra money to the smallest balance. When that first debt is paid off, its old payment rolls into the next-smallest debt, creating a larger payment as the plan moves forward.
The main reason people use the snowball method is psychological. Paying off a small balance quickly creates a visible win. That win can make the plan feel real, reduce overwhelm, and motivate you to keep going. The method may not always produce the lowest possible interest cost compared with the avalanche method, but it can be easier to stick with because progress feels concrete.
To use this calculator, enter each debt name, current balance, annual interest rate, and minimum monthly payment. Add any extra monthly amount you can consistently pay above your required minimums. The calculator estimates interest month by month, pays minimums on active debts, and applies the remaining payoff budget to the smallest starting balance among active debts until every debt reaches zero.
The results show the suggested payoff order, the month each debt may be paid off, total time to become debt-free, and estimated total interest paid. Treat the numbers as an educational planning estimate. Actual payoff dates can change if lenders calculate interest daily, minimum payments change, fees are added, or extra payments are not applied directly to principal.
If two debts have similar balances, you may still choose the one that feels more urgent, such as a collection account or a card you want to close. The calculator gives a structured starting point, but the best plan is the one you can follow consistently without missing required payments.
Why the first target might not be the first debt cleared
Keep only two debt rows. Enter Card A at $900, 12% APR and a $40 minimum. Enter Loan B at $1,200, 12% APR and a $400 minimum. Enter $50 extra, for a $490 fixed monthly budget. Card A has the smaller starting balance and receives the extra payment first.
After the first modeled month, Card A has $819 remaining and Loan B has $812. This calculator still uses the starting balances for priority; it does not reorder debts each month. Loan B nonetheless clears in month 4, before Card A in month 5, because its scheduled payment is much larger. Estimated total interest is $57.63.
Use the payoff month shown for each debt to see when it clears. Do not infer that order from the strategy name. In the model, any part of a scheduled payment that is no longer needed stays in the budget and can go to the next active debt, including in the payoff month. The snowball guide shows how to record the freed payment.
Sources and calculation notes
Our numerical examples use the monthly model described in our minimum-payment and priority rules. For account rules and terminology, see:
Content updated November 8, 2026. Examples are illustrations, not lender offers or account-specific payoff quotes.